 |
Whether or not the EU Emissions Trading System (EU ETS) will turn shippers towards greener fuel and inspire innovation remains to be seen. The current evidence that it will work is sparse. For example, industry expert Greg Knowler notes that Hapag-Lloyd expects just 1% of its annual fuel usage to be its ShipGreen product, and, in 2022, only 2% of Maersk’s 480,000 TEUs used its ECO delivery biofuel.[1]
Shipping may be late to the party, but data from current Carbon Pricing Instruments (CPIs) hardly paint an inspiring picture. A World Bank report from 2022 states that there are 37 carbon taxes and 34 emissions trading systems currently in operation around the world and that, in the majority of cases, the “carbon prices remain significantly below what is needed to achieve net zero by 2050 and meet the goals of the Paris Agreement”.[2] It describes this as a “gap between policies and pledges”.[3]
In a comprehensive review of 37 peer-reviewed, ex-post studies of emissions reductions caused by carbon pricing policies, Green points to four key findings.[4] First, that there is very little data on the issue. Second, that the effect on reductions for both taxes and ETSs is small, between 0% and 2% per annum. Third, that on the whole, taxes perform better than ETSs. Fourth, that the impact of the world’s largest scheme (the EU’s ETS) has so far been minimal.
These findings must be understood in the context of a general lack of data as well as the fact that those studies that have been carried out for the EU, for example, focused only on Phase 1, which was considered a pilot scheme where countries were allowed to set their own caps. Nonetheless, Green highlights how emissions prices have generally not been high enough to have an impact as well as the widely recognised problem of carbon leakage, where responsibility for emissions is simply shifted to another geographical area where there are less strict policies.
Zhu et al. explain that whether or not carbon pricing will have an effect depends on the bunker fuel price. In situations where the bunker fuel price is high (up to $583 per tonne), even countries with lax rules around emissions can inspire an emissions reduction of up to 8%.[5] When bunker prices are low ($348 per tonne), there are no emissions reductions. Koesler, Achtnicht and Köhler also suggest that bunker prices trump all other concerns around CO2 costs.[6]
Even if regulators manage to make enough of an intervention to change this, it could still be the case that biofuels will need to be cheaper than regular fuels because of costs incurred when changing the ship's fuel system. In the past, these changes have been absorbed by enhanced energy efficiency, so it is difficult to know where they will land with biofuels.
On the positive side, demand from traders and speculators has pushed ETS prices higher. And particular policy shifts are able to create expectation. For example, the publication of recommendations by the New Zealand Climate Change Commission in 2021 and the Republic of Korea’s change in climate targets heavily influenced and moved markets. Investors have managed to drive prices in the California-Quebec market.[7]
Perhaps the biggest challenge for the shipping industry will be offsets, where compliance is achieved by paying for emissions as part of other costs.[8] A study from Haites shows that even if there have been reductions in emissions in Europe of about 6.5% over several years, those countries without a carbon pricing policy reduced emissions faster than those with a tax![9]
There is also very little evidence that CPIs have resulted in more technological innovation. For example, Liliestam et al.’s study found no effects[10] and Van den Bergh and Savin found a small, but positive, effect on low-carbon innovation.[11]
One of the most cited innovations to tackle emissions is to reduce the speed of ships. The World Bank report points to studies that suggest 50% possible reductions from slower speeds, although this is largely dependent on fuel prices and charter and freight rates. A ship may slow down through certain parts of the route but speed up during others. Other possible innovations that may result from the EU ETS regulatory changes include designing more efficient ship hulls; more efficient optimization of ship routes to avoid bad weather, for example; the optimization of propulsion efficiency; sky sails (large sails that fly 200 metres above the ship and help pull it along); using low carbon fuels; and more efficient port management.
It is clear, however, that any technological innovations offshore will need to be matched by onshore infrastructure, and investors will want to ensure that ships use the facilities provided. The obligatory system in California ensures that ships use the onshore power facilities. In Norway, there were simultaneous government subsides for battery-powered ships and electric charging stations. But costs for onshore infrastructure are high and could be up to seven times more than onboard changes.[12]
|
FuelEU pooling drives surge in bio-LNG demand, Titan analysis finds
Clean fuel supplier's modelling shows pooling mechanism turning overcompliance into tradable value for LNG-fuelled ships. |
|
|
|
||
|
Ports told to prepare now for advanced nuclear power
Joint paper sets out a readiness pathway for ports facing nuclear-powered vessels, floating reactors and small modular units |
|
|
|
||
|
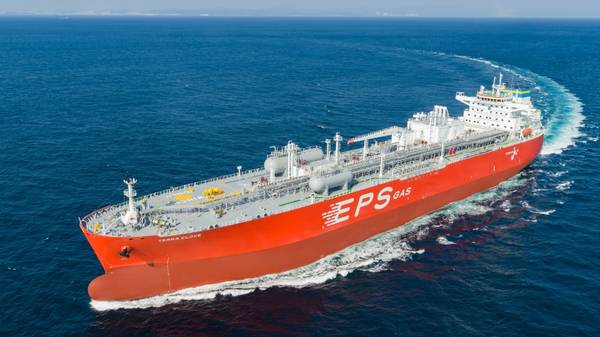
Eastern Pacific Shipping takes delivery of first ammonia dual-fuel VLAC
Terra Clove powered by first Everllence B&W 6G60ME-C10.5-LGIA ammonia dual-fuel two-stroke engine. |
|
|
|
||
|
Bureau Veritas approves WinGD's variable compression ratio technology for dual-fuel engines
Classification society grants type approval to engine technology enabling compression ratio adjustment across different marine fuels. |
|
|
|
||
|
Dual-fuel fleet passes 500 ships as investment tops $200bn
World Shipping Council data shows dual-fuel container ships and vehicle carriers growing fast, with IMO rules uncertain. |
|
|
|
||
|
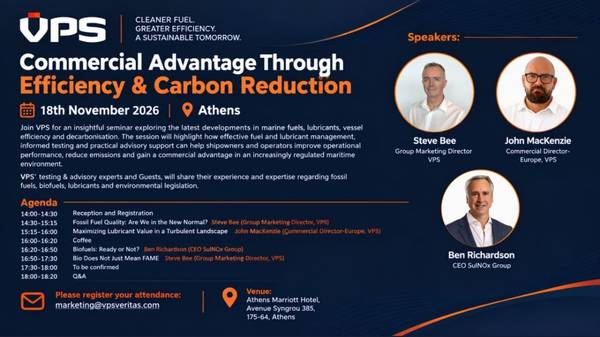
VPS to host Athens seminar on fuel efficiency and carbon reduction
VPS's final European round table of 2026 will cover marine fuels, lubricants and decarbonisation in Athens. |
|
|
|
||
|
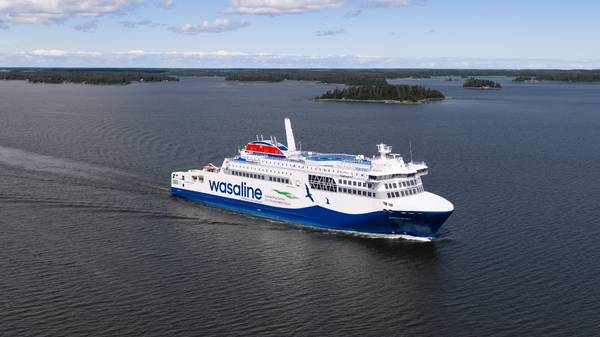
Wasaline secures locally produced biogas supply from St1 Biokraft for Vaasa–Umeå ferry
Agreement will supply 42 GWh of liquefied biogas annually, with deliveries due to start in January 2028. |
|
|
|
||
|
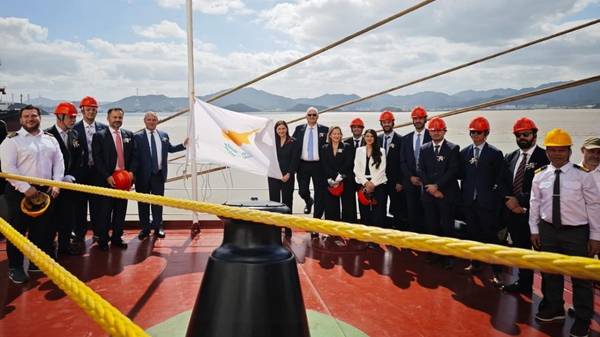
Safe Bulkers takes delivery of first dual-fuel methanol Kamsarmax newbuild
Kypros Island becomes the first dual-fuel bulker to enter the Cyprus Registry. |
|
|
|
||

|
PetroChina seeks LNG bunker trader to expand Asian marine fuel business
Role requires five to ten years of commercial experience in LNG, bunker trading, marine fuels, commodities, or energy trading. |
|
|
|
||
|
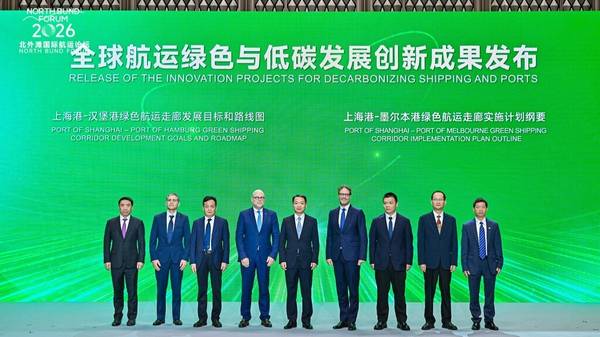
Shanghai and Melbourne ports move green shipping corridor into delivery phase
Ports launch implementation plan targeting green methanol, biofuels and shore power by 2035. |
|
|
|
||
| Who will bear the cost of EU emission allowances? [News & Insights] |
| How the EU ETS impacts non-EU nations and shippers [News & Insights] |
| Four cornerstones for a regulatory environment for sustainable fuels [News & Insights] |
| Formula for change: UECC solution for EU ETS gives clients clarity on emission costs | UECC [News & Insights] |
| Dual-fuel fleet passes 500 ships as investment tops $200bn [News & Insights] |
| WinGD CEO warns of mounting cost due to Net Zero Framework delay [News & Insights] |
| Maersk Tankers names second gas carrier in South Korea [News & Insights] |
| BSM takes over methanol-fuelled Maersk Torino, building alternative fuel experience [News & Insights] |
| Singapore completes world's largest ethanol bunkering operation [News & Insights] |