This is a legacy page. Please click here to view the latest version.
Mon 19 Feb 2018, 07:51 GMT

FIS expecting strong HSFO paper liquidity 'right up to deadline day' in 2020 and beyond


FIS bunker head warns firms against using 'proxy hedges' for MGO to cover all their marine fuel exposure.


London: River Thames with 'The Gherkin' in the background.
Image credit: File image / Pixabay
The head of the bunker desk at UK firm Freight Investor Services (FIS), Luke Longhurst, last week discussed how the upcoming sulphur cap regulation in 2020 is set to affect hedging in the cleared market.

Speaking during an industry seminar on sulphur regulation changes at the Baltic Exchange in London, Longhurst examined the compliance options available to shipowners and how hedging in the cleared market could be performed in each scenario.

LNG

In an evaluation of liquefied natural gas (LNG), Longhurst said he expected LNG to remain a small component of total bunker consumption in the run up to 2020.

"You're unlikely to be compliant by 2020 unless you have LNG-powered newbuilds under way, and, from a risk management perspective, I'm not aware of any liquid, cleared contract which could be used directly to hedge LNG for bunker use at the moment.

"LNG can be priced off other oil markers at present, but this can be very complex and difficult. Most LNG hedges are pipeline-related and not correlated to bunker fuel use," he pointed out.

Scrubbers with HSFO

Longhurst explained that a key advantage of installing scrubbers is that they enable shipping firms to continue using and hedging high-sulphur fuel oil (HSFO) at much cheaper rates than the lower-sulphur equivalent.

"For many years now, the most relevant contracts for the majority of the shipping world have been the high-sulphur Rotterdam 3.5% Barges and the Singapore 380 [cSt] contract. Both are hugely liquid markets on physical and paper side," he noted.

And whilst, according to Longhurst, HSFO currently accounts for around 75 percent of bunker demand, and one would therefore expect demand to decrease significantly as the migration towards gasoil and ultra-low-sulphur fuel oil (ULSFO) picks up, FIS does not foresee a significant drop in HSFO liquidity in the run up to 2020.

HSFO paper liquidity 'right up to deadline day'

Longhurst commented that, based on information from market makers and participants, the company expects there to be strong liquidity "right up to the deadline day and past 2020 for the HSFO paper markets".

"There is open interest in the HSFO market post-2020 and Platts have made it clear they will continue to offer the current HS market assessments beyond 2020," Longhurst remarked.

As a result, the FIS bunker specialist suggested that companies intending to install exhaust gas scrubbers could take advantage of the market situation by hedging their bunker costs at current levels, as spot prices could increase in the future.

"We believe you can lock in your HSFO rates now on the paper market cheaper than you might actually be paying physically at the time, come back-end 2019 / 20," Longhurst said.

Wait and see

Another option discussed by Longhurst was for bunker buyers to simply wait and see if more refiners make progress in mass-producing a compliant bunker-grade ULSFO, and if pricing agencies release new ULSFO price assessments for hedging.

Longhurst predicted that "a vast number of owners and operators" will decide to run their vessels on some form of ULSFO in 2020.

For shipping companies already running their ships on compliant marine gas oil (MGO), Longhurst suggested companies could hedge part of their bunker exposure with the existing gasoil contracts, such as low-sulphur gas oil and Singapore gas oil swaps, but noted: "I don't think the market sees this as the answer, and I don't think it's wise to use such proxy hedges on a full scale at this time for long-term exposure post 2020."

Given the various options that are available, Longhurst said he expected hedging demand to be fragmented between HSFO 380 (for ships with scrubbers), HSFO 180 (power generation), the new ULSFO 0.5% contract from Europe and Singapore, and Gasoil 10ppm for coastal operations.

Ambiguity

In terms of offering advice to market participants regarding hedging bunkers in 2020, Longhurst noted that there was "still too much ambiguity to offer any very firm advice right now".

"Ultimately, we need to wait before properly pricing any bunker costs post 2020. It would be naive of me to think that the transition from HSFO to LSFO will be smooth; there are questions of supply, storage and space of the various grades, blending and handling capabilities," he noted.

Longhurst added: "With so many questions, I think there will be teething issues and a lot of people will stick to what they know, which is HSFO up to deadline day; and when there is more clarity, you can look at gasoil in small clips. But I think clarity will first need to come from the pricing agencies - on when a LSFO contract for the main bunkering hubs will be available.

"Price discovery will be key, so we will keep a close eye on where the new spreads will trade between HSFO and LSFO - and the flat prices of each - and look at the different markets."

"Ultimately, we are all looking to avoid the doomsday scenario: if the supply of LSFO isn't there, but the enforcement is, then how will IMO respond - and the market deal with this - without stopping the shipping market in one fell swoop?"

Tool for reducing risk exposure

Longhurst was also keen to stress that fuel hedging is a tool for reducing exposure to risk.

"I think it's important to be clear on this: we still meet customers who have reservations about hedging their bunker exposure because they see this as gambling or speculating when in fact hedging is the exact opposite," Longhurst said.

"It's a tool that you can utilize to create some level of certainty against future price volatility. Fuel oil expenses represent a large and hugely volatile component of operating costs. It simply makes sense to take a proactive strategy and approach to budget management," Longhurst added.


Titan Optimus alongside Peony Leader vessel. FuelEU pooling drives surge in bio-LNG demand, Titan analysis finds  

Clean fuel supplier's modelling shows pooling mechanism turning overcompliance into tradable value for LNG-fuelled ships.

Keith Johnstone, Lloyd’s Register. Ports told to prepare now for advanced nuclear power  

Joint paper sets out a readiness pathway for ports facing nuclear-powered vessels, floating reactors and small modular units

Terra Clove vessel. Eastern Pacific Shipping takes delivery of first ammonia dual-fuel VLAC  

Terra Clove powered by first Everllence B&W 6G60ME-C10.5-LGIA ammonia dual-fuel two-stroke engine.

BV grants type approval to WinGD. Bureau Veritas approves WinGD's variable compression ratio technology for dual-fuel engines  

Classification society grants type approval to engine technology enabling compression ratio adjustment across different marine fuels.

Joe Kramek, WSC. Dual-fuel fleet passes 500 ships as investment tops $200bn  

World Shipping Council data shows dual-fuel container ships and vehicle carriers growing fast, with IMO rules uncertain.

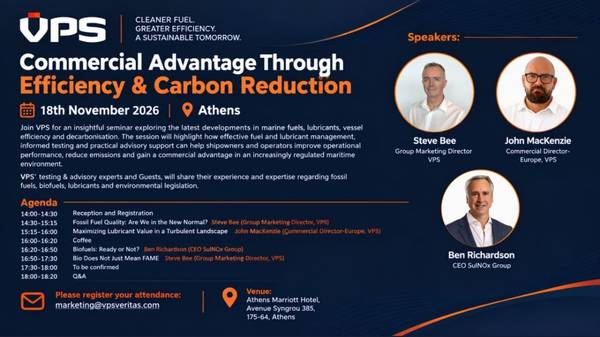
VPS Carbon Reduction seminar in Athens graphic. VPS to host Athens seminar on fuel efficiency and carbon reduction  

VPS's final European round table of 2026 will cover marine fuels, lubricants and decarbonisation in Athens.

Aurora Botnia vessel. Wasaline secures locally produced biogas supply from St1 Biokraft for Vaasa–Umeå ferry  

Agreement will supply 42 GWh of liquefied biogas annually, with deliveries due to start in January 2028.

Kypros Island delivery ceremony. Safe Bulkers takes delivery of first dual-fuel methanol Kamsarmax newbuild  

Kypros Island becomes the first dual-fuel bulker to enter the Cyprus Registry.

Singapore waterfront skyline. PetroChina seeks LNG bunker trader to expand Asian marine fuel business  

Role requires five to ten years of commercial experience in LNG, bunker trading, marine fuels, commodities, or energy trading.

Shanghai–Melbourne Green Shipping Corridor (GSC). Shanghai and Melbourne ports move green shipping corridor into delivery phase  

Ports launch implementation plan targeting green methanol, biofuels and shore power by 2035.


↑  Back to Top