This is a legacy page. Please click here to view the latest version.
Thu 28 Jan 2021, 17:44 GMT

Don't be fooled by low prices, IMO 2020 has changed bunkering forever | Søren Høll, KPI OceanConnect


KPI OceanConnect's CEO discusses price volatility, demand, risk and how procurement is more complex post-2020.


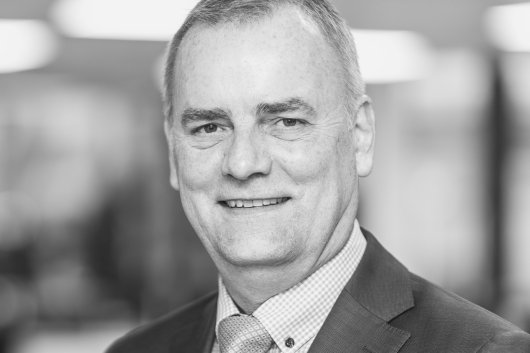
Søren Høll, CEO of KPI OceanConnect.
Image credit: KPI OceanConnect
By Søren Høll, CEO of KPI OceanConnect

This time last year, VLSFO prices stood at all-time highs. To much of the world, it seemed as though IMO 2020 might have permanently created large HSFO-VLSFO spreads, and a more fundamentally complex supply chain. As if that wasn't enough, rumours of quality management issues abounded. We now know just how rapidly things changed after those early weeks last year.

The Covid-19 pandemic has affected each bunkering hub differently, but it has universally created new challenges and operational dynamics. For example, although Panama has seen VLSFO sales increase since October 2020, it has not yet reached pre-pandemic levels, which stood at 388,307 tonnes in January 2020. On the other hand, despite the challenges posed by Covid-19 and IMO 2020, Singapore remains the world's top bunkering port with sales amounting to 49.8m tonnes in 2020, an increase of 5.0 percent year-on-year.

Demand for fuel from the cruise industry has remained at historic lows since April 2020, while other sectors – including containers – have seen bunker demand fluctuate massively. However, the reality is that except for cruise and some niche sectors such as pure car/truck carriers (PCTCs), most segments within the shipping industry have maintained high levels of operation.

What we thought we knew

When IMO 2020 first entered into force, there were concerns that some regions would not have the capacity to supply enough distillate fuels to meet both domestic and maritime demand. This has not proved to be the case. Many industries that would normally consume significant amounts of distillate fuels haven't due to coronavirus, and there has been more than enough compliant fuel to go around.

Covid-19 has dominated so much of our lives over the last year that it's easy to forget the major supply-side challenges at the start of 2020. Disagreements within OPEC+ over how much crude oil to produce led to a huge supply surplus just as demand started to fall. Some agreements have now been made to reign in oil production – including Saudi Arabia's planned 1m bpd cut – but latent supply is likely to exceed actual demand for some time to come as numerous key oil producers remain offline.

Vaccine rollouts are commencing across the world. There is hope that our lives will start to return to normal over the coming months, but some of the risks highlighted in 2019 may rear their head once more. Although the severest predictions of 12 months ago are unlikely to come to pass.

An unprecedented year

Bunker prices saw huge volatility in 2020. VLSFO in Rotterdam fell from roughly $600 per tonne in January to $150 per tonne in May and has since risen to the low $300s.

This may have been an extreme year, but it is a textbook example of why it's important to create comprehensive procurement and risk management strategies. As marine fuel is often the biggest single operational expense, unexpected spikes in cost can rapidly affect liquidity and profitability.

Over the last decade, we have seen big price moves become more common. Shipowners, charterers, and bunker suppliers can be left exposed by even modest changes in price, let alone the dramatic shifts we saw during 2020.

Proper risk management requires an expert understanding of the risks involved, and strong financial backing. For almost everyone this means working with trusted industry partners to develop policies and practises that enable shipowners or charterers to plan for any eventuality with confidence.

A new dynamic

The more marine fuels are regulated, the more complex procurement becomes. Since the arrival of ECAs and certainly post-IMO 2020, this has meant that the traditional, purely commoditised relationship between bunker suppliers and customers is no longer fit for purpose. Price will always remain important, but this new dynamic requires new strategies to deliver value.

Modern bunker traders need to act as trusted partners across the entire fuel procurement process, delivering expert technical and supply chain support while helping to manage risk. This means acting transparently and collaboratively to implement bespoke 'energy' strategies that meet a shipowner’s needs, now and in the future.

One of the most important aspects of a marine 'energy' strategy must be managing risk. This includes risks caused by price volatility, especially as global demand for distillate fuels increases; bunker traders must be equipped to safeguard their own liquidity in the face of price rises as well as a client's liquidity. Bunker traders must therefore be able to rely on financial strength and secure backing, as well as comprehensive insurance and specialist knowledge to deliver long term value.

As market needs change, companies operating within the bunker industry will need to adapt. Building the technical and local expertise, global coverage, and financial and organisational strength required will require some in the industry to revolutionise their business model.

Consolidation, such as the merger between KPI Bridge Oil and OceanConnect Marine to create KPI OceanConnect, will be a key driver in this transition and to accelerate the necessary changes. The added value for shipowners, operators and charterers of partnering with an organisation that not only meets this criteria, but delivers advanced marine energy solutions on a global scale by leveraging the enhanced synergies through a consultative approach are clear. We have brought together new ideas and ways of thinking, as well as more knowledge and expertise, to create a renewed energy in a changing marketplace.

Transformational industry change will never be straightforward. There will be challenges ahead for the entire bunkering sector, as old, purely transactional processes are replaced by comprehensive consulting services. At the same time, there is little doubt that bunkering will only get more complex over time and the value of taking a partnership-based approach will only increase further.


Sing Fuels logo. Sing Fuels seeks Asia-based supply trader to bolster bunker procurement team  

Singapore bunkering firm is recruiting a supply trader to manage marine fuel purchasing across Asia.

MOL joint naming ceremony. MOL names world's first ammonia-fuelled Capesize bulk carriers  

Naming of Ruri Mirai, Ruri Sekai and Ruri Hikari signals ammonia's arrival as a marine fuel for large bulk carriers.

Washington State Hybrid-Electric 160-Auto Ferry vessel render. ABB wins Washington State Ferries' third hybrid-electric vessel order  

ABB extends its role in the US ferry operator's electrification programme, which targets emission-free operations by 2050.

Aurora Borealis vessel. Kawasaki Heavy Industries delivers LPG-fuelled carrier Aurora Borealis  

Ship could also be modified in future to allow for ammonia-fuelled operation.

Rendering of Estonia's first shore-charged electric ferry. Estonian State Fleet's shore-charged electric ferry completes model testing in Germany  

Hull and propulsion tests show the vessel's energy consumption remains within contracted limits with room to spare.

Kypros Island vessel. Tsuneishi delivers first methanol dual-fuel Kamsarmax bulk carrier from Chinese yard  

Shipbuilder claims progress towards establishing a mass-production system for vessels designed to reduce environmental impact.

ZIM LNG container vessel. Los Angeles and Long Beach identify LNG and methanol as key near-term marine fuels  

Joint feasibility study maps out demand projections and infrastructure needs to support cleaner shipping fuels at San Pedro Bay

Alexander Treff, Christiania Energy, Christiania Energy welcomes student assistant to Copenhagen office  

Alexander Treff joins marine fuels firm while studying international business at Copenhagen Business School.

Carlotta Cosulich vessel. Cosulich Marine Energy takes delivery of third methanol-ready bunker tanker  

Carlotta Cosulich joins the group’s fleet, bringing its four-vessel bunkering programme closer to completion.

Rendering of a Wallenius Wilhelmsen vessel Wallenius Wilhelmsen orders four dual-fuel PCTCs, extends fleet renewal programme  

Shipping firm signs for LNG-fuelled car carriers with options for eight more, with deliveries from 2030.


↑  Back to Top