Thu 15 Feb 2018, 11:35 GMT

Oil and fuel oil hedging market update


By the Oil Desk at Freight Investor Services.


Commentary

Brent crude futures were at $65.05 per barrel at 0604 GMT, up $69 cents, or 1.1 percent, extending Wednesday's 2.6-percent climb. WTI crude futures were up $84 cents, or 1.4 percent, from their last settlement at $61.44 a barrel, adding to a 2.4-percent gain from the day before. A couple of observations were highlighted to me yesterday: US Domestic production for the week ending 9 Feb 10,271 mbd - up 1.3 mbd from a year ago, and OPEC + Russian production cuts being held through end-2018 - 1.8 mbd. Looking at these two figures you can see why many people are thinking that this is going to fall below $60. But as previously mentioned, do not underestimate OPEC's ability to pull this market up at any point they choose. They have ruined the party like that one friend on a night out who drinks too much and suddenly needs taking home. Just when you thought everything was finally taking a turn for the better, you had got past the usual point in the night they do it, then bam... he's giving the bouncer a Glaswegian kiss. OPEC have used the same card they have since 2016: the promise of further cuts. They say you can't teach a dog new tricks, well to be honest, they don't need to learn any new ones at the moment.

Fuel Oil Market (February 14)

The front crack opened at -9.00, weakening to -9.65 across the day. The Cal 19 was valued at -14.50.

Asia's front-month high-sulphur fuel oil crack extended gains, further narrowing its discount to Brent crude amid weaker crude oil price.

Meanwhile, cash premiums for cargoes of 380-cst fuel oil firmed slightly despite the absence of buying interest for cargoes of the fuel in the Singapore trading window.

Trade activity has been muted in the Singapore window in February with just 160,000 tonnes of fuel oil changing hands since the start of the month. By comparison, 540,000 tonnes of fuel oil cargoes were traded in the first half of January and 360,000 tonnes in the first half of February last year

Singapore weekly onshore fuel oil inventories dropped 4 percent from their highest so far this year to 22.828 million barrels (about 3.41 million tonnes) in the week ended Feb. 13. Inventories dropped despite a 15% increase in weekly net fuel oil imports.

Economic Data and Events

* ~12pm: Russian refining maintenance schedule from ministry

* 1:30pm: U.S. Initial Jobless Claims for Feb. 10, est. 228k (prior 221k)

* 1:30pm: U.S. Empire Manufacturing for Feb., est. 18 (prior 17.7)

* 2:15pm U.S. Industrial Production m/m for Jan., est. 0.2% (prior 0.9%)

* Russian Urals crude 5-day program for March

* China markets closed for Chinese New Year holiday, through Feb. 21

Singapore 380 cSt

Mar18 - 358.50 / 360.50

Apr18 - 358.25 / 360.25

May18 - 357.75 / 359.75

Jun18 - 357.00 / 359.00

Jul18 - 355.75 / 357.75

Aug18 - 354.75 / 356.75

Q2-18 - 357.75 / 359.75

Q3-18 - 354.75 / 356.75

Q4-18 - 349.75 / 352.25

Q1-19 -341.50 / 344.00

CAL19 - 309.75 / 312.75

CAL20 - 237.00 / 242.00

Singapore 180 cSt

Mar18 - 365.25 / 367.25

Apr18 - 364.75 / 366.75

May18 - 364.25 / 366.25

Jun18 - 363.75 / 365.75

Jul18 - 362.50 / 364.50

Aug18 - 361.50 / 363.50

Q2-18 - 364.25 / 366.25

Q3-18 - 361.50 / 363.50

Q4-18 - 356.75 / 359.25

Q1-19 - 349.25 / 351.75

CAL19 - 319.00 / 322.00

CAL20 - 252.75 / 257.75

Rotterdam Barges

Mar18 345.50 / 347.50

Apr18 345.50 / 347.50

May18 344.75 / 346.75

Jun18 343.75 / 345.75

Jul18 342.25 / 344.25

Aug18 340.50 / 342.50

Q2-18 335.00 / 337.00

Q3-18 340.25 / 342.25

Q4-18 331.50 / 334.00

Q1-19 323.00 / 325.50

CAL19 286.00 / 289.00

CAL20 223.00 / 228.00


Andre M ammonia-fuelled gas carrier. China delivers first domestically built ammonia-fuelled gas carrier  

CCS-classed vessel becomes the world's second ammonia-fuelled gas carrier, testing rules for the IMO's zero-carbon shipping transition.

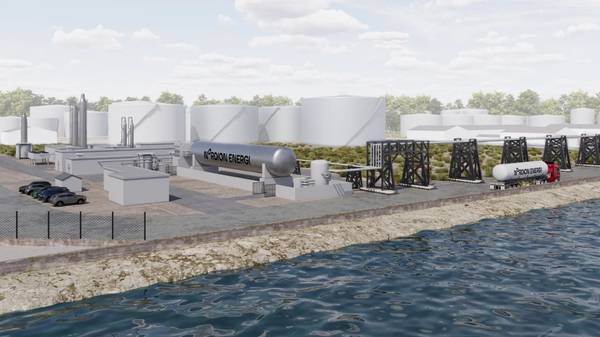
Nordion Energi liquefied biogas (LBG) facility render. Storage tank installed as Gothenburg's LBG bunkering plant advances towards 2027 completion  

Nordion Energi's liquefied biogas facility at the Port of Gothenburg takes a step forward with tank installation.

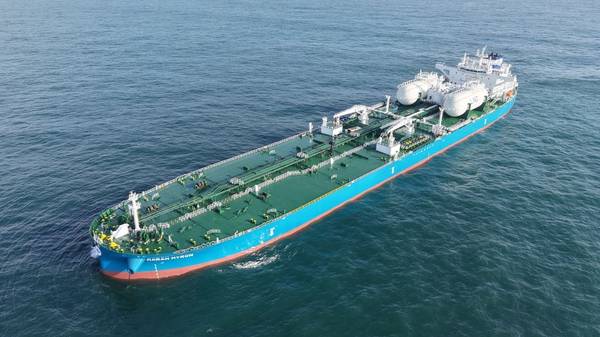
Maran Myron vessel. Maran Tankers takes delivery of dual-fuel Suezmax Maran Myron  

Vessel is sixth dual-fuel tanker in eight-vessel series built by New Times Shipbuilding.

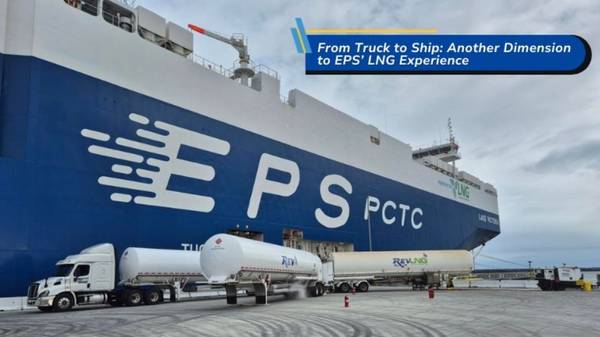
Lake Victoria truck-to-ship (TTS) bunkering operation. EPS completes first truck-to-ship LNG bunkering operation in Davisville  

Fuel delivered to the pure car and truck carrier Lake Victoria whilst at berth.

Maritime and Port Authority of Singapore logo. MPA opens applications for LNG floating storage unit licences  

Singapore invites applications for up to two LNG floating storage unit licences to bolster bunkering supply resilience.

Rasmus Frimann Nielsen and Lars Zimmermann, Everllence. Everllence's small-bore GenSet orders surpass 2,000 in 2026  

Engine maker reports strong order intake across its small-bore portfolio, citing demand for reliable, fuel-flexible auxiliary power.

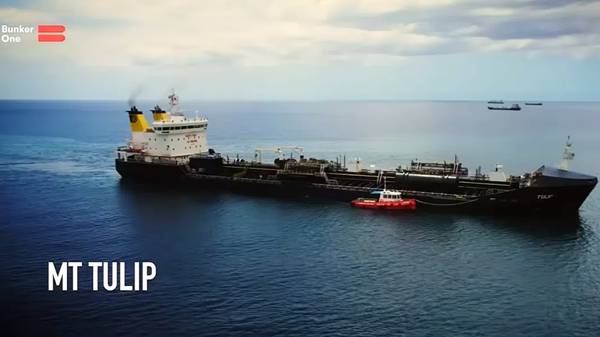
MT Tulip bunker tanker. Bunker One renews MT Tulip charter, plans mass flow meter upgrade in Mauritius  

Bunker One is keeping its bunker tanker in Mauritius while adding flow metering technology to improve delivery transparency.

COP31 panel discussion. Fund for Energy Efficiency Technologies becomes first to adopt revised Singapore-Asia Taxonomy  

FEET's adoption coincides with Lloyd's Register's independent review of GCMD's methodology for quantifying fuel savings from wind-assisted propulsion systems.

Arsenio Dominguez, IMO Secretary-General. IMO chief urges states to enforce safety rules in Strait of Hormuz amid rising attacks  

Arsenio Dominguez says more than 130 attacks on commercial vessels have been verified since February, with at least 25 seafarers killed.

OOCL Wisdom ship-to-ship (STS) bunkering operation at Xiamen Port. Xiamen Port launches 'green methanol bunkering' with OOCL Wisdom  

Boxship received 1,005 tonnes of methanol, corresponding to a reduction of more than 1,600 tonnes in carbon emissions, says COSCO Shipping.