This is a legacy page. Please click here to view the latest version.
Thu 19 Jul 2018, 08:55 GMT

Oil and fuel oil hedging market update


By the Oil Desk at Freight Investor Services.


Commentary

Brent closed up $0.74 last night to $72.90 and WTI closed at $68.76, up $0.68. Brent spent much of the day dragging it's knuckles until EIA showed a gasoline draw, finally. We rallied up to $73 from being down to $71.20 earlier in the day. However, don't let these number deceive you, my oily chums. Crude showed a build, which was surprising considering the pipeline from Canada is still down, refinery runs were down and, more importantly, US oil production hit 11mn bpd. That's more than Saudi, and a mozzie's whisker away from Russia. In January of this year I said the following regarding US oil production. "End 2018 it is going to be 11mn bpd". I thought I was being fairly bullish by saying end 2018 but they've actually gone and done it in 6 months! That is a staggering production increase of 30% in 2 years. How long has Trump been President? Hmmm. If the U.S. can now sort it transportation capacity bottleneck, it will be teetering on being the world's largest oil producer - at the current rate of growth - in just over a year. The crude market looks like it is in for a correction over the next few weeks. The Summer of discontent? The only fly in the ointment is that Midland vs WTI futures is trading around -8.30 for Cal 19. I read a piece this morning by Mr Ed Bell that the Dallas Fed reckon that the breakeven for Permian is $53 bucks. So it's kind of on the edge right now for Cal 19. Let's see. In other news, fuel oil continues its resolute strength. The crack may not have moved on the big dumps in crude price we had the other day, but you are going to see it react in the next few weeks as supplies continue to dwindle. Fuel oil inventories are nigh on at a record low, but you don't see any data about that moving the market, do you? Residual or not, perhaps it is time to look at the bottom of the tower instead of constantly looking up and shouting "Rapunzel, Rapunzel, show me your driving season stats?" #welovefueloilthemost. Keep your eye on cable and the Brent spreads. Good day.

Fuel Oil Market (Jul 18)

The front crack opened at -8.60, weakening to -8.70, before strengthening to -8.55. The Cal 19 was valued at -15.35

The front-month fuel oil crack widened its discount to Brent crude on Wednesday, slipping further away from recent highs despite sharp declines in crude oil prices over the past week.

While fuel oil crack discounts typically narrow as crude prices weaken, industry participants said the weaker crack values this week could be a result of profit-taking after weeks of active trade. Industry participants also said the wider crack discount could be sign of gradually increasing fuel oil output after months of shrinking fuel oil inventories across key storage hubs

Fuel oil inventories at the Fujairah slipped 1.2 percent, or 121,000 barrels (about 18,000 tonnes), to a two-week low of 9.779 million barrels (1.46 million tonnes) in the week ended July 16.

Economic data/events (Times are London.)

* 1:30pm: Philadelphia Fed Business Outlook, July

* 1:30pm: U.S. Initial Jobless Claims, July 14

* 1:30pm: U.S. Continuing Claims, July 7

* 2:45pm: Bloomberg Consumer Comfort, July 15

* 2:45pm: Bloomberg Economic Expectations, July

* Singapore onshore oil-product stockpile data

* Russian refining maintenance schedule from ministry

* API's Monthly Statistical Report

Singapore 380 cSt

Aug18 - 427.75 / 429.75

Sep18 - 419.75 / 421.75

Oct18 - 414.50 / 416.50

Nov18 - 411.00 / 413.00

Dec18 - 407.75 / 409.75

Jan19 - 404.50 / 406.50

Q4-18 - 411.25 / 413.25

Q1-19 - 402.00 / 404.00

Q2-19 - 392.25 / 394.75

Q3-19 - 366.50 / 369.00

CAL19 - 372.50 / 375.50

CAL20 - 298.25 / 304.25

Singapore 180 cSt

Aug18 - 436.25 / 438.25

Sep18 - 429.00 / 431.00

Oct18 - 424.50 / 426.50

Nov18 - 421.25 / 423.25

Dec18 - 418.25 / 420.25

Jan19 - 415.25 / 417.25

Q4-18 - 421.50 / 423.50

Q1-19 - 412.75 / 414.75

Q2-19 - 404.00 / 406.50

Q3-19 - 382.00 / 384.50

CAL19 - 387.00 / 390.00

CAL20 - 321.50 / 327.50

Rotterdam 3.5%

Aug18 - 405.75 / 407.75

Sep18 - 400.25 / 402.25

Oct18 - 396.00 / 398.00

Nov18 - 392.00 / 394.00

Dec18 - 388.50 / 390.50

Jan19 - 386.25 / 388.25

Q4-18 - 392.25 / 394.25

Q1-19 - 383.50 / 385.50

Q2-19 - 372.75 / 375.25

Q3-19 - 347.50 / 350.00

CAL19 - 350.00 / 353.00

CAL20 - 285.75 / 291.75

BP  

Titan Optimus alongside Peony Leader vessel. FuelEU pooling drives surge in bio-LNG demand, Titan analysis finds  

Clean fuel supplier's modelling shows pooling mechanism turning overcompliance into tradable value for LNG-fuelled ships.

Keith Johnstone, Lloyd’s Register. Ports told to prepare now for advanced nuclear power  

Joint paper sets out a readiness pathway for ports facing nuclear-powered vessels, floating reactors and small modular units

Terra Clove vessel. Eastern Pacific Shipping takes delivery of first ammonia dual-fuel VLAC  

Terra Clove powered by first Everllence B&W 6G60ME-C10.5-LGIA ammonia dual-fuel two-stroke engine.

BV grants type approval to WinGD. Bureau Veritas approves WinGD's variable compression ratio technology for dual-fuel engines  

Classification society grants type approval to engine technology enabling compression ratio adjustment across different marine fuels.

Joe Kramek, WSC. Dual-fuel fleet passes 500 ships as investment tops $200bn  

World Shipping Council data shows dual-fuel container ships and vehicle carriers growing fast, with IMO rules uncertain.

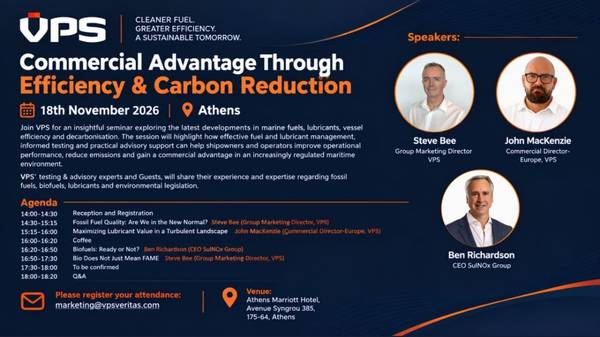
VPS Carbon Reduction seminar in Athens graphic. VPS to host Athens seminar on fuel efficiency and carbon reduction  

VPS's final European round table of 2026 will cover marine fuels, lubricants and decarbonisation in Athens.

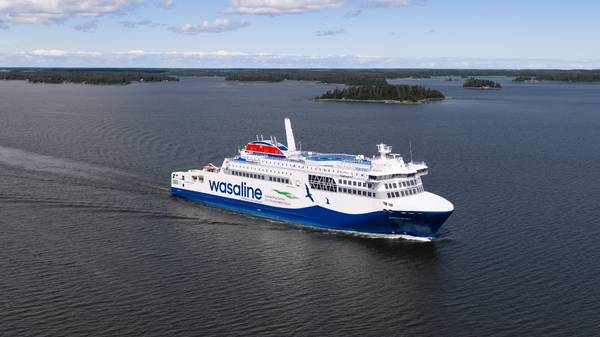
Aurora Botnia vessel. Wasaline secures locally produced biogas supply from St1 Biokraft for Vaasa–Umeå ferry  

Agreement will supply 42 GWh of liquefied biogas annually, with deliveries due to start in January 2028.

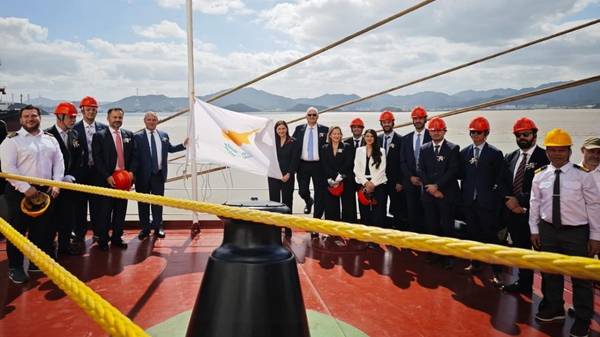
Kypros Island delivery ceremony. Safe Bulkers takes delivery of first dual-fuel methanol Kamsarmax newbuild  

Kypros Island becomes the first dual-fuel bulker to enter the Cyprus Registry.

Singapore waterfront skyline. PetroChina seeks LNG bunker trader to expand Asian marine fuel business  

Role requires five to ten years of commercial experience in LNG, bunker trading, marine fuels, commodities, or energy trading.

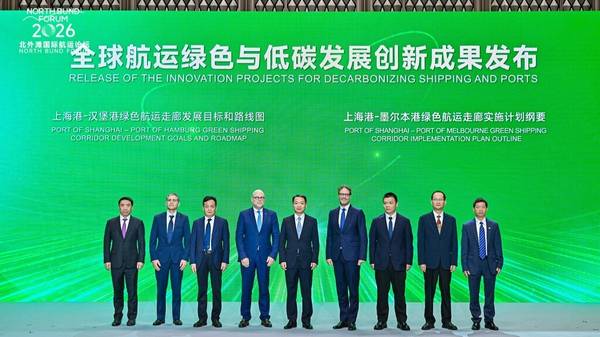
Shanghai–Melbourne Green Shipping Corridor (GSC). Shanghai and Melbourne ports move green shipping corridor into delivery phase  

Ports launch implementation plan targeting green methanol, biofuels and shore power by 2035.


↑  Back to Top