This is a legacy page. Please click here to view the latest version.
Fri 9 Feb 2018, 09:22 GMT

Oil and fuel oil hedging market update


By the Oil Desk at Freight Investor Services.


Commentary

Brent futures were down 44 cents or 0.7%, at $64.37 a barrel by around 07:00 GMT. U.S. WTI crude was down 62 cents, or 1%, at $60.53 a barrel, having settled down 1% in the previous session at its lowest close since Jan. 2. I saw a great quote this morning: 'Bets on further rising oil and metals prices, for example by hedge funds, have climbed to excessively bullish levels'. Excessively bullish. I can see why this kind of comment would come from an oil end user; anything above $0 is excessively bullish. But from a bank analyst, with hedge funds up to their armpits in long oil positions, after a technical pull back, with high OPEC compliance, growing China demand - they have the power to push this back up again. The only excessive thing this morning is the use of excessive. Excessivity is rife. Looking at a more macro level, I don't think it presumptuous to assume that generally for commodities we are in a long term bull trend. The growing world economy, political dangers, uncertainty, there's also the practical implications of the new arms race that could occur. There is an Asian race between U.S. allies (eg Japan, South Korea) against China and North Korea, there's NATO against Russia, and I don't think it too implausible for the Trump administration to try for a 'Falklands moment' - a quick war that the whole country is behind to boost popularity. Let's just hope it doesn't turn into another Vietnam or Cuban Missile Crisis. But before you send all your thoughts on why this market is going to collapse, just bear in mind that over the last year and a half, people have been saying it's going to collapse, and in that time it has gone from $26 to over $70. Just think that small players with their little exposure and trading capacity aren't going to outweigh the ability of big market players to move this upwards. Yes, over a longer time period you may be proved right, but that will be in the terms of the long positions, when they have had enough of holding them and sell out for a tidy profit.

Fuel Oil Market (February 8)

The front crack opened at -10.45, strengthening to -10.15, before weakening to -10.30. The Cal 19 was valued at -14.00.

Rising Singapore fuel oil inventories weighed on Asia's fuel oil market sentiment on Thursday, dragging time spreads, fuel oil cracks and cash differentials of the fuel lower, trade sources said.

In a sign of growing prompt supplies, the March/April time spread for 380 cSt fuel oil flipped to a contango of about 30 cents a tonne on Thursday, down from a backwardation of about 10 cent per tonne in the previous session.

Singapore fuel oil inventories rose for a fourth straight week, climbing 6% to a 2018 high of 23.782 million barrels (about 3.55 million tonnes) in the week ended Feb. 7.

China's crude oil imports in January rose 20% year-on-year to a record 40.64 million tonnes, or 9.57 million barrels per day (bpd).

Economic Data and Events

* 3pm: U.S. Wholesale Inventories for Dec. M/M, est. 0.2%, (prior 0.2%)

* 6pm: Baker Hughes rig count

* ~6pm: ICE weekly commitments of traders report for Brent, gasoil

* 8:30pm: CFTC weekly commitments of traders report on various U.S. futures and options contracts

Singapore 380 cSt

Mar18 - 353.75 / 355.75

Apr18 - 353.75 / 355.75

May18 - 353.75 / 355.75

Jun18 - 353.25 / 355.25

Jul18 - 352.25 / 354.25

Aug18 - 351.00 / 353.00

Q2-18 - 353.75 / 355.75

Q3-18 - 351.25 / 353.25

Q4-18 - 346.50 / 349.00

Q1-19 - 338.50 / 341.00

CAL19 - 309.50 / 312.50

CAL20 - 241.75 / 246.75

Singapore 180 cSt

Mar18 - 359.50 / 361.50

Apr18 - 359.75 / 361.75

May18 - 360.00 / 362.00

Jun18 - 359.25 / 361.25

Jul18 - 358.50 / 360.50

Aug18 - 357.25 / 359.25

Q2-18 - 359.75 / 361.75

Q3-18 - 357.50 / 359.50

Q4-18 - 353.25 / 355.75

Q1-19 - 346.75 / 349.25

CAL19 - 318.50 / 321.50

CAL20 - 252.50 / 257.50

Rotterdam Barges

Mar18 340.75 / 342.75

Apr18 340.75 / 342.75

May18 340.50 / 342.50

Jun18 340.00 / 342.00

Jul18 338.75 / 340.75

Aug18 336.75 / 338.75

Q2-18 340.25 / 342.25

Q3-18 337.00 / 339.00

Q4-18 328.75 / 331.25

Q1-19 320.50 / 323.00

CAL19 286.50 / 289.50

CAL20 227.25 / 232.25

BP  

Titan Optimus alongside Peony Leader vessel. FuelEU pooling drives surge in bio-LNG demand, Titan analysis finds  

Clean fuel supplier's modelling shows pooling mechanism turning overcompliance into tradable value for LNG-fuelled ships.

Keith Johnstone, Lloyd’s Register. Ports told to prepare now for advanced nuclear power  

Joint paper sets out a readiness pathway for ports facing nuclear-powered vessels, floating reactors and small modular units

Terra Clove vessel. Eastern Pacific Shipping takes delivery of first ammonia dual-fuel VLAC  

Terra Clove powered by first Everllence B&W 6G60ME-C10.5-LGIA ammonia dual-fuel two-stroke engine.

BV grants type approval to WinGD. Bureau Veritas approves WinGD's variable compression ratio technology for dual-fuel engines  

Classification society grants type approval to engine technology enabling compression ratio adjustment across different marine fuels.

Joe Kramek, WSC. Dual-fuel fleet passes 500 ships as investment tops $200bn  

World Shipping Council data shows dual-fuel container ships and vehicle carriers growing fast, with IMO rules uncertain.

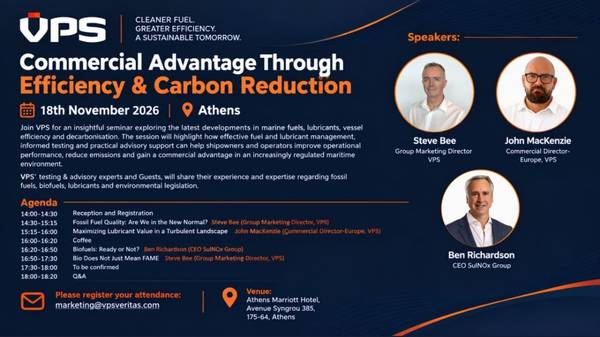
VPS Carbon Reduction seminar in Athens graphic. VPS to host Athens seminar on fuel efficiency and carbon reduction  

VPS's final European round table of 2026 will cover marine fuels, lubricants and decarbonisation in Athens.

Aurora Botnia vessel. Wasaline secures locally produced biogas supply from St1 Biokraft for Vaasa–Umeå ferry  

Agreement will supply 42 GWh of liquefied biogas annually, with deliveries due to start in January 2028.

Kypros Island delivery ceremony. Safe Bulkers takes delivery of first dual-fuel methanol Kamsarmax newbuild  

Kypros Island becomes the first dual-fuel bulker to enter the Cyprus Registry.

Singapore waterfront skyline. PetroChina seeks LNG bunker trader to expand Asian marine fuel business  

Role requires five to ten years of commercial experience in LNG, bunker trading, marine fuels, commodities, or energy trading.

Shanghai–Melbourne Green Shipping Corridor (GSC). Shanghai and Melbourne ports move green shipping corridor into delivery phase  

Ports launch implementation plan targeting green methanol, biofuels and shore power by 2035.


↑  Back to Top