This is a legacy page. Please click here to view the latest version.
Tue 21 Nov 2017, 09:01 GMT

Oil and fuel oil hedging market update


By the Oil Desk at Freight Investor Services.


Commentary

Brent crude futures, the international benchmark for oil prices, were at $62.20 per barrel at 03:01 GMT, $8 cents above their last close, and U.S. WTI crude futures were at $56.50 a barrel, also up $8 cent from their last settlement. Come on people, the market is boring enough without trotting out the same headlines over and over again. 'Oil prices steady as rising U.S. output undermines OPEC cuts', 'Market waits for OPEC meeting'. Some interesting points not being talked about in these stories, oil hipster time. U.S. rig count remained unchanged. It wasn't long ago that people were losing their minds over the increasing rig count; why has this not gone to the moon with the increasing crude price? We've hardly had any movement since breaking through the $60 level. This is an important point to dwell on, especially with the news that ConocoPhillips is looking to invest all its new project money in shale oil. The implications of the IMO 2020 regulations are going to start to impact the market, and I bet if you are a tanker owner you are wringing your hands as there is going to be a lot of refined product that needs to be transported to ports to cater for the new demand. Goodie for you. WTI is looking like the younger brother of Brent who has now grown up and is far bigger and better. Its problems of investment for capacity increases and readjusting trade routes will have a profound effect on the market. Yes OPEC cut, yes inventories, blah blah, we get it and know it. But if you want to stay ahead of the curve, there's plenty of other things we could be taking about.

Fuel Oil Market (November 20)

The front crack opened at -7.95, weakening to -8.00, before strengthening to -7.90, ending -8.00. The Cal 18 was valued at -7.85.

The second-month EW arbitrage spread of 380 narrowed to a near two-month low as arrivals into Singapore through December are expected to improve.

Recently, weaker fuel oil prices in northwest Europe due to rising Russian fuel oil exports after the conclusion of the refinery maintenance season there, as well as relatively weaker tanker charter rates, have encouraged some suppliers to lock in fresh supplies into Singapore

Total fuel oil flows into East Asia for November were poised to close at nine-month high of around 7 million tonnes, boosted by recovering Western arrivals, near record-high inflows from the Middle East and 11-month high intra-Asia volumes.

Economic Data/Events: (UK times)

* 1:30pm: Chicago Fed Nat Activity Index, Oct.

* 3pm: U.S. Existing Home Sales, Oct.

* 9:30pm: API issues weekly U.S. oil inventory report

Singapore 380 cSt

Dec17 - 361.25 / 363.25

Jan18 - 360.00 / 362.00

Feb18 - 358.75 / 360.75

Mar18 - 357.50 / 359.50

Apr18 - 356.00 / 358.00

May18 - 354.25 / 356.25

Q1-18 - 358.75 / 360.75

Q2-18 - 354.75 / 356.75

Q3-18 - 349.50 / 352.00

Q4-18 - 344.50 / 347.00

CAL18 - 352.25 / 355.25

CAL19 - 317.75 / 322.75

Singapore 180 cSt

Dec17 - 365.25 / 367.25

Jan18 - 364.25 / 366.25

Feb18 - 363.50 / 365.50

Mar18 - 362.75 / 364.75

Apr18 - 361.75 / 363.75

May18 - 361.00 / 363.00

Q1-18 - 363.50 / 365.50

Q2-18 - 361.00 / 363.00

Q3-18 - 356.00 / 358.50

Q4-18 - 351.00 / 353.50

CAL18 - 358.50 / 361.50

CAL19 - 326.50 / 331.50

Rotterdam 380 cSt

Dec17 341.75 / 343.75

Jan18 341.75 / 343.75

Feb18 341.50 / 343.50

Mar18 341.00 / 343.00

Apr18 340.00 / 342.00

May18 339.00 / 341.00

Q1-18 341.50 / 343.50

Q2-18 339.50 / 341.50

Q3-18 334.50 / 337.00

Q4-18 326.00 / 328.50

CAL18 335.25 / 338.25

CAL19 296.75 / 301.75


Gas Bauhinia vessel. Jiangnan Shipyard delivers dual-fuel VLEC to Southwest Shipping  

Delivery of Gas Bauhinia closes out a series of very large ethane carriers built for Southwest Shipping.

Lotte Fine Chemical and Hoegh Autoliners logos. Lotte Fine Chemical and Höegh Autoliners sign MoU on green ammonia bunkering  

Chemicals firm and car carrier operator to collaborate on ammonia fuel supply chain and bunkering infrastructure.

Brave Bulker vessel. Tsuneishi-Cebu delivers third methanol dual-fuelled Kamsarmax bulker  

Vessel features dual-fuel design that allows the use of methanol alongside conventional fuel.

LFC 5000 vessel render. Everllence to supply 175D GenSets for battery-hybrid live-fish carrier  

Four 12V175D-MEV variable-speed GenSets will power a well-boat for Norway's Brønnbåt Nord.

Bunker Partner logo. Bunker Partner seeks marine fuel trader for Singapore office  

Prior experience in marine fuels and good knowledge of the Singapore and APAC bunker markets required.

Stanley George, VPS. VPS manager joins ISO working group on alternative marine fuels  

Stanley George will represent the UK on ISO’s alternative marine fuels specification group.

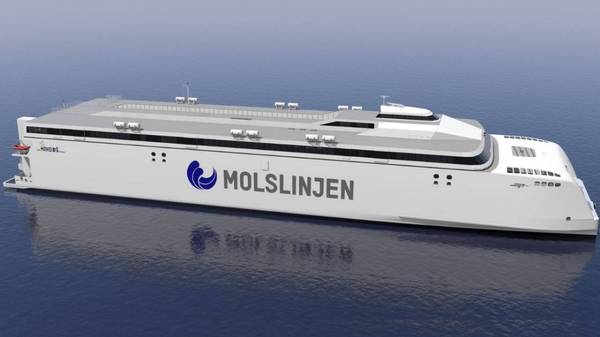
Molslinjen vessel render. AYK Energy secures battery contract for Molslinjen's electric fast ferries  

Battery maker to supply 165MWh for three electric catamarans after cutting system weight by nearly half.

Giosue Vezzuto, RINA. Giosuè Vezzuto named CEO of RINA Services, taking charge of marine and certification arm  

Naval engineer with nearly three decades at RINA succeeds Paolo Moretti to lead the group's marine and certification division.

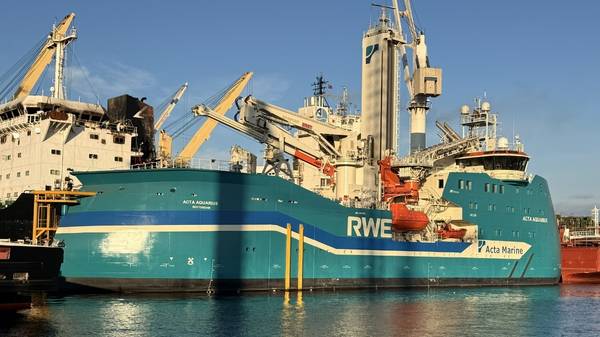
Acta Aquarius vessel. Acta Marine completes four-vessel newbuild programme with delivery of methanol dual-fuel Acta Aquarius  

Dutch offshore support vessel operator takes delivery of its fourth Tersan-built CSOV, featuring dual-fuel methanol propulsion.

Wind-assisted vessel illustration. Lloyd's Register backs GCMD methodology for verifying wind propulsion fuel savings  

Independent review aims to boost confidence in wind-assisted propulsion performance and unlock sustainable finance for energy-efficiency retrofits.


↑  Back to Top


 Recommended