This is a legacy page. Please click here to view the latest version.
Tue 7 Nov 2017, 08:50 GMT

Oil and fuel oil hedging market update


By the Oil Desk at Freight Investor Services.


Brent closed up $2.20 last night to $64.27 and WTI closed at $57.35, up $1.71. Crude is up as you can see. Quite a rally we witnessed last night. One minute I had a mouthful of Spaghetti Bolognese, the next minute crude was up 2 bucks. Why? To be honest, I think a lot of people are sitting there scratching their heads this morning. All I know is that this market is a fickle one and let's remember, elephants never forget. The bears are there in the background and they have long memories too. However, even elephants mess up sometimes and it seems as if the days of "lower for longer" are over. Yeah right. The market seems to be buying into the events that are happening in Saudi Arabia and the new regime that may follow, which apparently means that this is bullish for the oil sector. Nigeria have gladly followed this up with "of course we will support an extension". I bet you will, mate, considering you're exempt from any production cuts and are just benefiting from higher flat price. I think the market seems to be missing something so obvious, however. The kind of obvious like when you meet someone for the first time and they've got a really big spot on their forehead and you can't stop staring at it lest you try. Higher crude prices inevitably means higher product prices. I have written about refining margins being at record highs this year and these same margins have not adjusted down with higher crude prices. The market is all about "demand getting stronger", well I'll tell you something: Brent has rallied close to 40% in a year. That is 40% more to fill up your car with VW's favourite diesel or some super-high-octane gasoline for your pickup truck or for Micheal O'Leary to charge you a new "jet fuel tax" for your summer holiday next year.. With prices up, demand will surely wane - and round we go again.

Fuel Oil Market (November 6)

The front crack opened at -7.85, strengthening to -7.70, before weakening to -7.90. The Cal 18 was valued at -7.65.

The discount of Asia's fuel oil crack to crude oil widened slightly but was still "strong" in spite of crude oil prices rising to their highest since July 2015. The front-month 180-cst fuel oil crack to Brent crude widened its discount by 8 cents a barrel to minus $3.69 a barrel, holding near its five-week high of minus $3.55 a barrel seen on Nov. 2.

Fuel oil cracks rose to a near five-week high on expectations of tightening fuel oil supplies into 2018 amid shrinking output and fewer arbitrage bookings into Asia, as well as firm demand for the industrial fuel. Meanwhile, the front-month 180-cst fuel oil crack to Dubai crude widened its discount further from a near sixweek high seen on Wednesday as rising inventories in key storage hubs weighed. Fuel oil stocks in ARA oil hub rose for a second straight week, up 2%, or 22,000 tonnes, to 1.356 million tonnes in the week to Nov. 2. Compared to last year, ARA inventories are up 137% and are well above the five-year average of 851,000 tonnes for this time of year.

Taiwan's Formosa Petrochemical Corp plans to shut a crude oil unit and several secondary units for maintenance at its 540,000 bpd Mailiao refinery in 2018.

Economic Data/Events: (UK times)

* 12pm: U.S. MBA mortgage applications for week ended Nov. 3 (prior -2.6%)

* 1:30pm: OPEC's World Oil Outlook to be published, with press conference by Secretary-general Mohammad Barkindo, Vienna

** Bloomberg-compiled refinery snapshot, looking at key outages at refineries in the U.S. and Canada, and providing offline capacity projections for crude units and FCCs

** Platts gasoline, naphtha and LPG conference, Rotterdam, final day

** EIA releases Short Term Energy Outlook

Singapore 380 cSt

Dec17 - 376.00 / 378.00

Jan18 - 373.50 / 375.50

Feb18 - 371.25 / 373.25

Mar18 - 369.50 / 371.50

Apr18 - 367.75 / 369.75

May18 - 366.00 / 368.00

Q1-18 - 371.50 / 373.50

Q2-18 - 366.00 / 368.00

Q3-18 - 360.00 / 362.50

Q4-18 - 354.00 / 356.50

CAL18 - 361.50 / 364.50

CAL19 - 321.50 / 326.50

Singapore 180 cSt

Dec17 - 380.75 / 382.75

Jan18 - 379.00 / 381.00

Feb18 - 376.75 / 378.75

Mar18 - 375.50 / 377.505

Apr18 - 374.25 / 376.25

May18 - 372.75 / 374.75

Q1-18 - 377.25 / 379.25

Q2-18 - 372.50 / 374.50

Q3-18 - 366.50 / 369.00

Q4-18 - 361.50 / 364.00

CAL18 - 368.00 / 371.00

CAL19 - 330.25 / 335.25

Rotterdam 380 cSt

Dec17 355.50 / 357.50

Jan18 353.50 / 355.50

Feb18 352.50 / 354.50

Mar18 351.50 / 353.50

Apr18 350.50 / 352.50

May18 349.25 / 351.25

Q1-18 352.50 / 354.50

Q2-18 349.25 / 351.25

Q3-18 343.50 / 346.00

Q4-18 334.75 / 337.25

CAL18 343.75 / 346.75

CAL19 301.75 / 306.75

BP  

Titan Optimus alongside Peony Leader vessel. FuelEU pooling drives surge in bio-LNG demand, Titan analysis finds  

Clean fuel supplier's modelling shows pooling mechanism turning overcompliance into tradable value for LNG-fuelled ships.

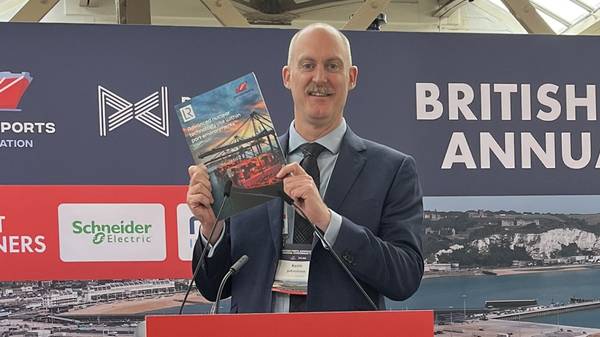
Keith Johnstone, Lloyd’s Register. Ports told to prepare now for advanced nuclear power  

Joint paper sets out a readiness pathway for ports facing nuclear-powered vessels, floating reactors and small modular units

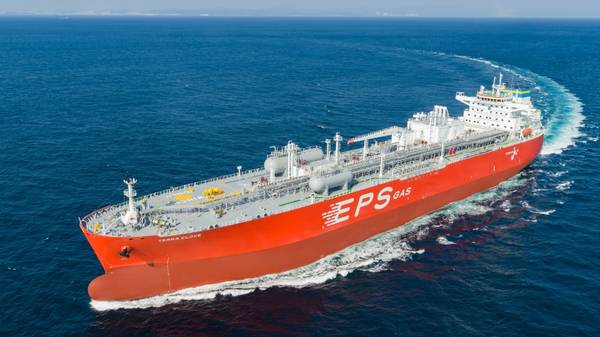
Terra Clove vessel. Eastern Pacific Shipping takes delivery of first ammonia dual-fuel VLAC  

Terra Clove powered by first Everllence B&W 6G60ME-C10.5-LGIA ammonia dual-fuel two-stroke engine.

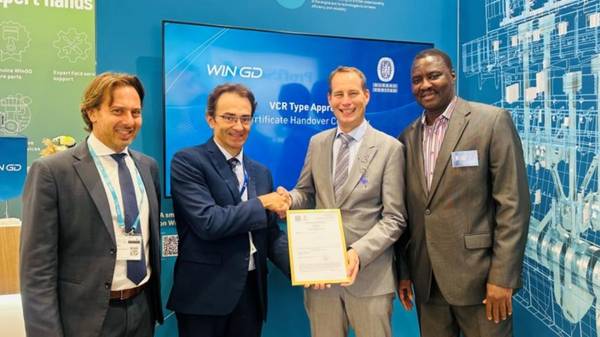
BV grants type approval to WinGD. Bureau Veritas approves WinGD's variable compression ratio technology for dual-fuel engines  

Classification society grants type approval to engine technology enabling compression ratio adjustment across different marine fuels.

Joe Kramek, WSC. Dual-fuel fleet passes 500 ships as investment tops $200bn  

World Shipping Council data shows dual-fuel container ships and vehicle carriers growing fast, with IMO rules uncertain.

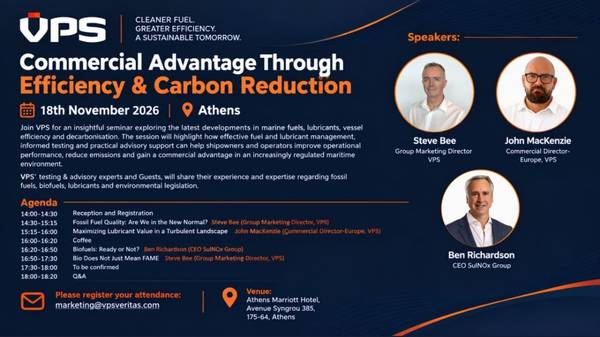
VPS Carbon Reduction seminar in Athens graphic. VPS to host Athens seminar on fuel efficiency and carbon reduction  

VPS's final European round table of 2026 will cover marine fuels, lubricants and decarbonisation in Athens.

Aurora Botnia vessel. Wasaline secures locally produced biogas supply from St1 Biokraft for Vaasa–Umeå ferry  

Agreement will supply 42 GWh of liquefied biogas annually, with deliveries due to start in January 2028.

Kypros Island delivery ceremony. Safe Bulkers takes delivery of first dual-fuel methanol Kamsarmax newbuild  

Kypros Island becomes the first dual-fuel bulker to enter the Cyprus Registry.

Singapore waterfront skyline. PetroChina seeks LNG bunker trader to expand Asian marine fuel business  

Role requires five to ten years of commercial experience in LNG, bunker trading, marine fuels, commodities, or energy trading.

Shanghai–Melbourne Green Shipping Corridor (GSC). Shanghai and Melbourne ports move green shipping corridor into delivery phase  

Ports launch implementation plan targeting green methanol, biofuels and shore power by 2035.


↑  Back to Top