|
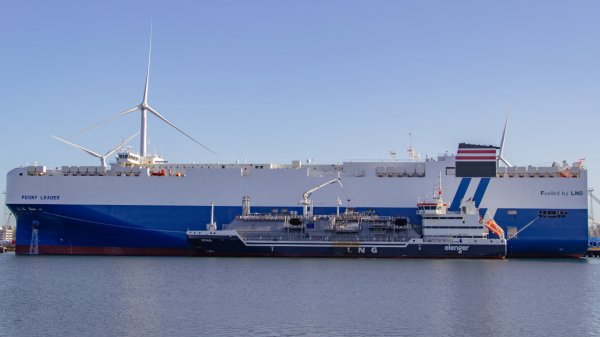
FuelEU pooling drives surge in bio-LNG demand, Titan analysis finds
Clean fuel supplier's modelling shows pooling mechanism turning overcompliance into tradable value for LNG-fuelled ships. |
|
|
|
||
|
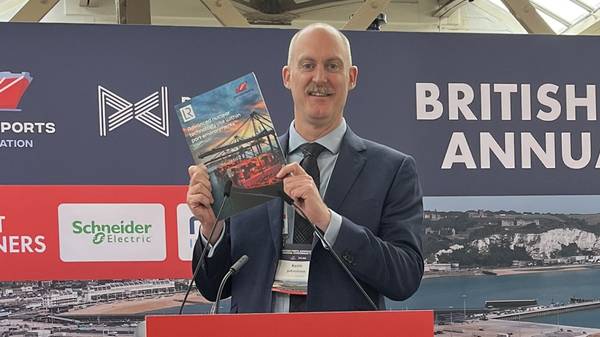
Ports told to prepare now for advanced nuclear power
Joint paper sets out a readiness pathway for ports facing nuclear-powered vessels, floating reactors and small modular units |
|
|
|
||
|
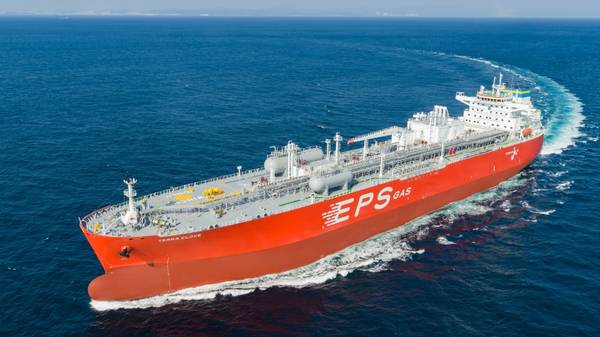
Eastern Pacific Shipping takes delivery of first ammonia dual-fuel VLAC
Terra Clove powered by first Everllence B&W 6G60ME-C10.5-LGIA ammonia dual-fuel two-stroke engine. |
|
|
|
||
|
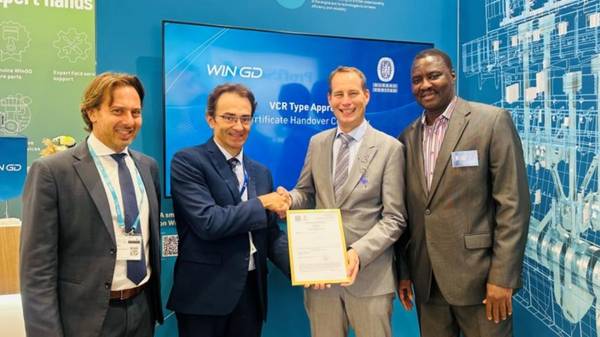
Bureau Veritas approves WinGD's variable compression ratio technology for dual-fuel engines
Classification society grants type approval to engine technology enabling compression ratio adjustment across different marine fuels. |
|
|
|
||
|
Dual-fuel fleet passes 500 ships as investment tops $200bn
World Shipping Council data shows dual-fuel container ships and vehicle carriers growing fast, with IMO rules uncertain. |
|
|
|
||
|
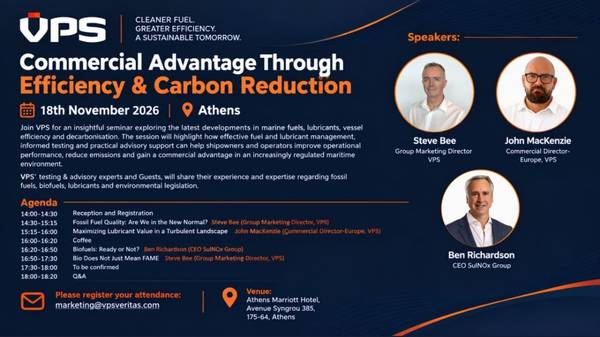
VPS to host Athens seminar on fuel efficiency and carbon reduction
VPS's final European round table of 2026 will cover marine fuels, lubricants and decarbonisation in Athens. |
|
|
|
||
|
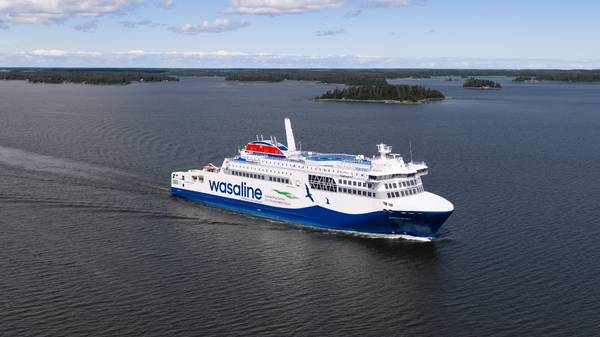
Wasaline secures locally produced biogas supply from St1 Biokraft for Vaasa–Umeå ferry
Agreement will supply 42 GWh of liquefied biogas annually, with deliveries due to start in January 2028. |
|
|
|
||
|
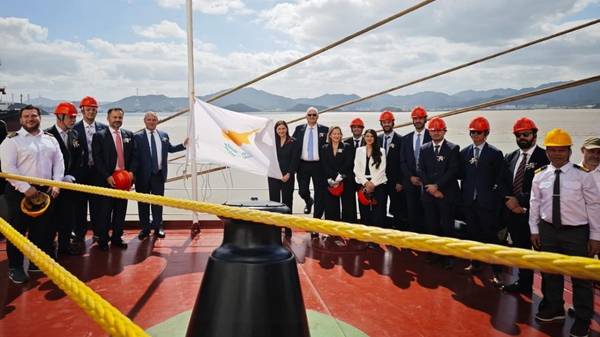
Safe Bulkers takes delivery of first dual-fuel methanol Kamsarmax newbuild
Kypros Island becomes the first dual-fuel bulker to enter the Cyprus Registry. |
|
|
|
||

|
PetroChina seeks LNG bunker trader to expand Asian marine fuel business
Role requires five to ten years of commercial experience in LNG, bunker trading, marine fuels, commodities, or energy trading. |
|
|
|
||
|
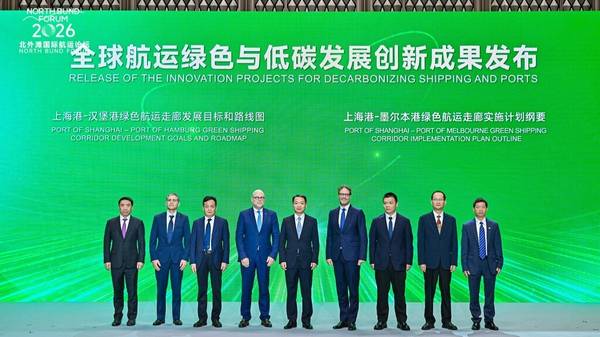
Shanghai and Melbourne ports move green shipping corridor into delivery phase
Ports launch implementation plan targeting green methanol, biofuels and shore power by 2035. |
|
|
|
||
| Anemoi Marine Technologies appoints Lloyd’s Register technical director to oversight committee [News & Insights] |
| NYK operates methanol-fuelled bulk carrier for BHP, claims 65% emissions cut [News & Insights] |
| Galveston LNG Bunker Port signs vessel partnership with TOTE Services [News & Insights] |
| Compagnie Maritime Nantaise wins Bpifrance backing for space logistics vessel decarbonisation project [News & Insights] |
| IBIA opens voting for board elections with 11 candidates competing for four positions [News & Insights] |