This is a legacy page. Please click here to view the latest version.
Wed 11 Oct 2017, 09:02 GMT

Oil and fuel oil hedging market update


By the Oil Desk at Freight Investor Services.


By the Oil Desk at Freight Investor Services Ltd.

Commentary

Brent closed up $0.82 last night to $56.61 and WTI closed at $50.92, up $1.34. Quite a rally yesterday. But what was it on the back of? Well, I couldn't say for absolutely sure. Some are claiming that it's owing to Mr Barkindo's promises about taking "extraordinary" steps - you know my view on this over the last two days. Others are claiming it's because of the Saudi 560kbpd cuts on crude allocation, but it can't be that because exports are actually going to rise more than they did last month. So what is the cause? Well, it's pretty simple really, WTI climbed more than $0.50 cents per bbl over Brent yesterday on the close. The WTI/Brent spread is now -5.30, this time last week it was -6. We see this spread coming in even further the more US exports rise and the more OPEC say they are going to cut. The answer to the intraday rallies is quite simply that the U S are now flexing their muscles and bidding flat price up before selling it when it touches $55. "Simples", as that stupid annoying meerkat would say. All the talk recently has been that the market is on the road to recovery. But what does "recovery" mean? The last time Brent was above $60 per bbl was July 2015. In July 2014, Brent was over $110 per bbl. Do people really want $110 per bbl oil again? Well, if you're a rich oil oligarch who needs to buy a new gold-plated car. then yes. Most readers of this commentary will have a vested interest in the oil business, but I don't believe any one of you want to actually pay double or triple the cost right now to fill your car up every week to take your kinds to ballet/football/rugby/drama class/horse riding etc etc etc, do you? We have been stuck in a rangebound market for a while now and I don't see how we can break out of it when US shale is so adaptable to spikes in flat price. OPEC report and API out later so watch flat price with caution.

Fuel Oil Market (October 10)

*The front crack opened at -8.15, weakening to -8.20, strengthening -8.10, finishing at -8.15. The Cal 18 was valued at -8.25.

*Cash premiums of Asia's 380-cst high-sulphur fuel oil fell to a near one-month low amid weaker deal values in the Platts pricing window.

*Lower expectations of tight Singapore fuel oil supplies in the coming months has scaled back some gains in 380-cst fuel oil cash premiums and time spreads which rose to multi-month highs in late-September.

*Shipping fuel suppliers are filing millions of dollars in claims over unpaid marine fuel bills against now-defunct Singapore-based peer Universal Energy, formerly one of the city state's largest bunker suppliers but which has now entered liquidation. Overall creditor claims against Universal Energy total to about $100 million, and has sent shockwaves across Singapore's bunker fuel market.

Economic Data/Events: (UK times)

* 11am-12pm: OPEC monthly market report, including secondary- source production estimates for September

* 12pm: U.S. MBA mortgage applications for week ended Oct. 6 (prior -0.4%)

* ~5pm: U.S. EIA releases monthly short-term energy outlook, or STEO, and Winter Fuels Outlook

* 9:30pm: U.S. API issues weekly oil inventory report (delayed due to U.S. holiday Mon.)

* No exact timing

** Caspian CPC, Azeri Supsa crude programs for November

** Genscape weekly ARA crude stockpiles report

** Argus European and Global Crude Summit, Geneva, final day

** Calgary Energy Roundtable, with executives from Kinder Morgan, Suncor

Singapore 380 cSt

Nov17 - 324.00 / 326.00

Dec17 - 322.25 / 324.25

Jan18 - 320.50 / 322.50

Feb18 - 319.00 / 321.00

Mar18 - 318.00 / 320.00

Apr18 - 317.25 / 319.25

Q1-18 - 319.25 / 321.25

Q2-18 - 316.50 / 318.50

Q3-18 - 313.50 / 316.00

Q4-18 - 311.25 / 313.75

CAL18 - 314.25 / 317.25

CAL19 - 296.75 / 301.75

CAL20 - 280.50 / 287.50

Singapore 180 cSt

Nov17 - 328.75 / 330.75

Dec17 - 327.50 / 329.50

Jan18 - 326.75 / 328.75

Feb18 - 325.75 / 327.75

Mar18 - 325.00 / 327.00

Apr18 - 324.25 / 326.25

Q1-18 - 326.00 / 328.00

Q2-18 - 323.25 / 325.25

Q3-18 - 320.00 / 322.50

Q4-18 - 318.75 / 321.25

CAL18 - 321.25 / 324.25

CAL19 - 305.75 / 310.75

CAL20 - 289.75 / 296.75

Rotterdam 380 cSt

Nov17 305.50 / 307.50

Dec17 301.75 / 303.75

Jan18 301.75 / 303.75

Feb18 301.50 / 303.50

Mar18 301.25 / 303.25

Apr18 300.75 / 302.75

Q1-18 301.50 / 303.50

Q2-18 299.75 / 301.75

Q3-18 296.50 / 299.00

Q4-18 292.00 / 294.50

CAL18 297.50 / 300.50

CAL19 278.50 / 283.50

CAL20 260.50 / 267.50


Founded in 2002, Freight Investor Services is a specialist in dry bulk and commodity derivatives, including cargo freight, iron ore, fertilizer and bunker fuel. The company has offices in London, Dubai, Singapore and Shanghai.

For further details about fuel oil swaps or to discuss trading opportunities, please contact Andrew Cullen, Client Relations & Development Manager, on +44 207 090 1126, or email AndrewC@freightinvestor.com.

BP  

Empire State Building, New York. Maersk Oil Trading seeks New York-based fuel trader for Americas bunker business  

Firm looking for candidates with 'several years' of relevant experience in fuel trading, bunker trading, fuel marketing, cargo trading, or similar.

Taha Karakan and Aydın Yıldız, Alkagesta. Alkagesta completes Energy Petrol takeover, appoints new marine sales leadership in Türkiye  

Acquisition includes eight marine fuel supply vessels and a long-term lease of tank capacity in Gebze.

Venezuela flag. TFG Marine extends Caribbean bunkering reach into Venezuela  

Majority Trafigura-owned bunker supplier partners with Impordiesel to offer marine fuel across Venezuelan ports and coastal waters.

IMO LNG-fuelled ship safety training in Japan. IMO trains regional instructors to teach seafarers LNG fuel safety  

Trainers from four Southeast Asian nations completed a Japan-based workshop on LNG bunkering and emergency response skills.

Rotterdam Shore Power construction at ROG Ship Repair's yard. Shore power construction begins at Rotterdam ship repair yard  

Rotterdam Shore Power has started building shore power facilities at ROG's Waalhaven yard, targeting completion by summer 2027.

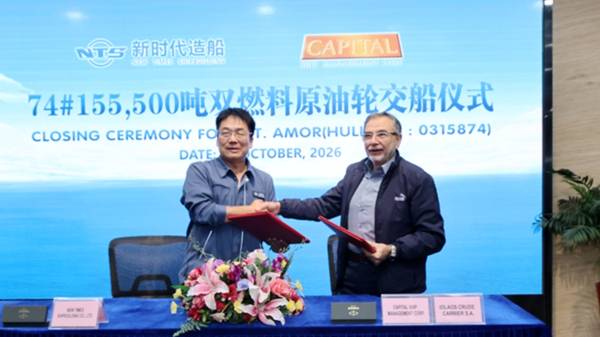
Closing ceremony of vessel with builder’s hull no. 0315874. LNG dual-fuel crude tanker handed over to Capital  

Jiangsu New Times Shipbuilding delivers the 155,500-DWT LNG dual-fuel crude oil vessel Amor.

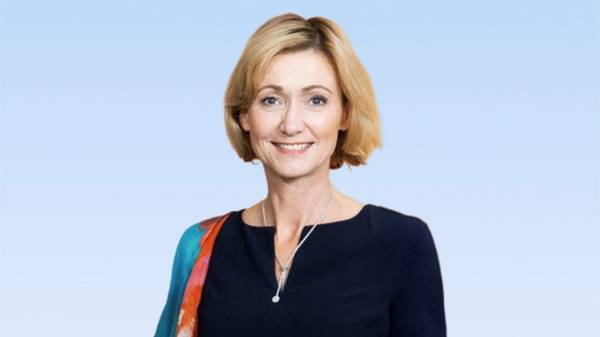
Lowina Lundstrom, Gasum. Gasum names Lowina Lundström as vice president, biogas  

Former EIT InnoEnergy executive joins Gasum's management team to lead biogas business development from 1 December.

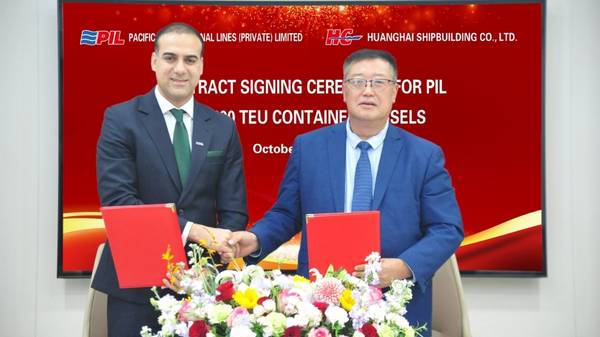
PIL and Huanghai Shipbuilding contract signing. PIL orders seven methanol-ready feeder vessels from Huanghai Shipbuilding  

Singapore carrier's 1,400-TEU newbuilds will boost intra-Asia capacity and support its 2050 net zero target.

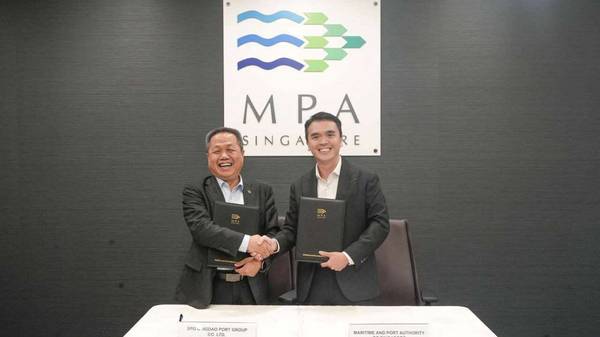
MPA and Qingdao Port work plan signing ceremony. Singapore and Qingdao sign work plan to advance green and digital shipping corridors  

MPA and Shandong Port Group’s Qingdao Port have agreed to pursue methanol bunkering pilots and data-sharing initiatives between the two ports.

Delfin Midstream FLNG unit render. Wärtsilä to supply dual-fuel engines and thrusters for Delfin Midstream's FLNG vessel  

Finnish technology group lands propulsion order for first floating LNG vessel built for US Gulf export project.


↑  Back to Top