This is a legacy page. Please click here to view the latest version.
Tue 10 Oct 2017, 07:48 GMT

Oil and fuel oil hedging market update


By the Oil Desk at Freight Investor Services.


By the Oil Desk at Freight Investor Services Ltd.

Commentary

Brent closed up $0.17 last night to $55.79 and WTI closed at $49.58 up $0.29. Yesterday the word of the day was "extraordinary". Today the word of the day seems to be "please". The general secretary of OPEC came out this morning and said: "We urge our friends, in the shale basins of North America to take this shared responsibility with all seriousness it deserves, as one of the key lessons learnt from the current unique supply-driven cycle". Ahem. I touched on this very subject a few months ago. The dynamic of shale oil is that production is reactive to flat price a lot faster than those of the more traditional ways of producing, i.e. OPEC. Most US producers are financed by the normal reserve base lending banks in the US who will ensure caveats are in each financing agreement to either start hedging the minute oil prices get to a certain level (I'd imagine this number to be in the low 50's based on the fact Eagle Ford average breakeven is $48 per bbl); or in the case of the newer producers, they will be asked to buy put options before funds are released to start nodding some donkeys. So why Mr Barkindo, with all respect, do you think that new technology, 21st century financing and having the ability to use modern derivative instruments isn't going to stop the US producers doing what they need to do? The US isn't as reliant on the older school of balancing federal budgets with oil derived income - they are diverse and the above evidences such. Look, I'm all for stability, don't get me wrong, but treating the US as allies in the oil market battle is like asking Cersei Lannister for a lift to the pub. Disaster. Winter is coming.

Fuel Oil Market (October 9)

*The front crack opened at -8.10, weakening to -8.15, strengthening -7.95, finishing at -8.10. The Cal 18 was valued at -8.25.

*Selling pressure continued to weigh on Asia's Nov/Dec 380-cst fuel oil time spread, which slipped to its lowest since Sept. 12 on Monday

*Expectations of narrowing near-term supplies had recently boosted the front month time spread to a nine month high in late-September but has trended lower since the start of October, possibly as a result of fresh suppliers being booked for arrival in the coming months. By contrast, strong buying interest for physical cargoes of 380-cst fuel oil lifted cash premiums of the mainstay fuel to a one-week high.

*OPEC and other oil producers may need to take "some extraordinary measures" next year to rebalance the oil market, the OPEC secretary-general said on Sunday

Economic Data/Events: (UK times)

*7:45am: France industrial production y/y for Aug., est. 1.5% (prior 3.7%)

*9am: Italy industrial production m/m for Aug., est. 0.1% (prior 0.1%)

*9:30am: U.K.

**Industrial production m/m for Aug., est. 0.2% (prior 0.2%)

**Manufacturing production m/m for Aug., est. 0.2% (prior 0.5%)

*Today:

**India Energy Forum, final day

**Argus European and Global Crude Summit, Geneva, with executives from Shell, BP, Gunvor, among others, 1st day of 2

**Bloomberg-compiled weekly snapshot of key U.S. refinery outages with offline capacity projections for CDU, FCC units

*U.S. Columbus Day holiday

Singapore 380 cSt

Nov17 - 318.75 / 320.75

Dec17 - 317.25 / 319.25

Jan18 - 315.50 / 317.50

Feb18 - 314.00 / 316.00

Mar18 - 313.00 / 315.00

Apr18 - 312.25 / 314.25

Q1-18 - 314.25 / 316.25

Q2-18 - 311.75 / 313.75

Q3-18 - 308.75 / 311.25

Q4-18 - 306.75 / 309.25

CAL18 - 310.00 / 313.00

CAL19 - 294.00 / 299.00

CAL20 -279.25 / 286.25

Singapore 180 cSt

Nov17 - 323.75 / 325.75

Dec17 - 322.50 / 324.50

Jan18 - 321.75 / 323.75

Feb18 - 320.75 / 322.75

Mar18 - 320.00 / 322.00

Apr18 - 319.25 / 321.25

Q1-18 - 321.00 / 323.00

Q2-18 - 318.50 / 320.50

Q3-18 - 315.25 / 317.75

Q4-18 - 314.25 / 316.75

CAL18 - 317.00 / 320.00

CAL19 - 303.00 / 308.00

CAL20 - 288.50 / 295.50

Rotterdam 380 cSt

Nov17 300.75 / 302.75

Dec17 297.25 / 299.25

Jan18 297.25 / 299.25

Feb18 297.00 / 299.00

Mar18 296.75 / 298.75

Apr18 296.25 / 298.25

Q1-18 297.00 / 299.00

Q2-18 295.75 / 297.75

Q3-18 293.25 / 295.75

Q4-18 289.00 / 291.50

CAL18 293.25 / 296.25

CAL19 274.25 / 279.25

CAL20 256.25 / 263.25


Founded in 2002, Freight Investor Services is a specialist in dry bulk and commodity derivatives, including cargo freight, iron ore, fertilizer and bunker fuel. The company has offices in London, Dubai, Singapore and Shanghai.

For further details about fuel oil swaps or to discuss trading opportunities, please contact Andrew Cullen, Client Relations & Development Manager, on +44 207 090 1126, or email AndrewC@freightinvestor.com.

BP  

Bjorn Hauschild, IBT Bunkering & Trading. IBT Bunkering & Trading appoints Sales Support Specialist  

Björn Hauschild joins from shipyard broker CombiTrade.

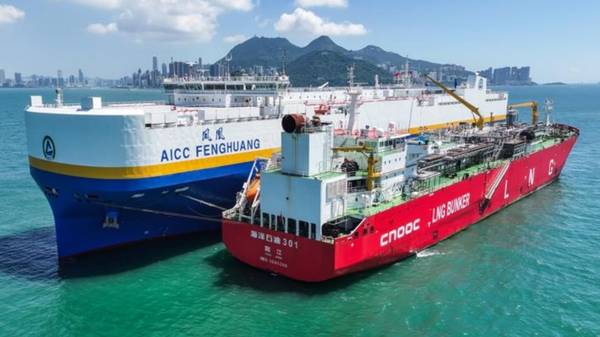
Haiyang Shiyou 301 ship-to-ship (STS) LNG bunkering operation. CLPe and CNOOC complete Hong Kong's first LNG bunkering of a pure car and truck carrier  

Ship-to-ship operation delivered around 2,600 cbm of LNG to dual-fuel vessel AICC Fenghuang.

Mercuria logo. Mercuria seeks senior sales and account manager for bunker delivery platform  

Role can be based either remotely or at one of its offices in London, Geneva, Athens or Las Palmas.

Molgas Energy logo. Molgas Energy Group appoints Riaan van Kralingen as head of clean fuels  

Van Kralingen will oversee the company's liquefied biomethane and EU allowance portfolios, succeeding Caspar Gooren.

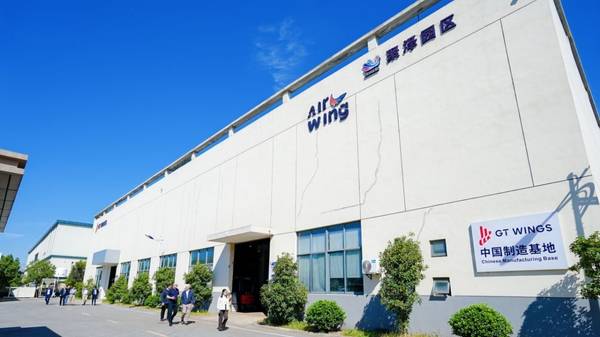
GT Wings manufacturing facility. GT Wings launches compact AirWing S Jet Sail for smaller vessels  

Wind propulsion developer adds lightweight unit to AirWing range as first customer-ordered AirWing20 units near completion.

Cargo ship bow in dry dock. LR publishes retrofit guidance covering alternative fuels and energy-saving devices in one framework  

New Guidance Notes address LNG, methanol, ammonia, hydrogen, wind-assisted propulsion and air lubrication retrofits for existing ships.

Spirit of Toulouse fitted with rotor sails. LD Armateurs' Spirit of Toulouse fitted with six Norsepower rotor sails  

Six 35m rotor sails installed on the first of three methanol-capable ro-ro ships chartered by Airbus.

Steel-cutting ceremony for bunker vessel. Maritima holds steel-cutting ceremony for Cap Morgiou, first of two Petroineos bunker vessels  

Construction starts on bunker vessel able to carry conventional and low-carbon marine fuels, with delivery expected in early 2028.

MPA and SIBCON 2026 logos. Singapore launches series of measures at SIBCON 2026  

MPA announces LNG storage licences, digital bunkering grants and electric harbour craft incentives at 24th conference.

SIBCON 2026 pre-conference event. VPS outlines marine fuel standards and quality data at SIBCON 2026  

VPS's Rahul Choudhuri addresses Singapore's evolving fuel standards and the quality of conventional fuels and biofuels.


↑  Back to Top